Professor David McLean on Finance and Growth
Professor David McLean (Georgetown University) has been a Visiting Distinguished Professor at the Aalto Department of Finance since last year. This August David taught a new GSF doctoral course on “Finance and Growth: The Roles of Financial Development, Institutions, and Shareholder Primacy”.
We spoke to David about his academic career and research, his thoughts on economic growth and his book on the pursuit of profits.
1. How did you come to an academic career? Did you ever consider an alternative path, or was it clear from the outset that you would pursue a PhD and become a finance professor?
I was an economics undergraduate, and after college I worked for a few years before going back for an MBA. In my first finance class, the professor, Hank Bessembinder, explained that he was a financial economist — essentially, an economist who studies financial assets and financial markets. For some reason, that description struck a chord with me. It connected finance to the economics I had already enjoyed studying and made me realize that this was something I could imagine doing as a career. That was really the beginning of my interest in pursuing a PhD and eventually becoming a finance professor. It certainly was not a path I had planned from the outset.
2. What inspires you most in your work as a professor? Is it research, teaching, your students, academic freedom, or something else?
Early in my career, I was more narrowly focused on research and on establishing myself in the profession. Earning tenure, which is largely determined by research and publication, can be a real struggle, so young professors tend to be very research-focused. After tenure, and especially as I have gotten older, I have come to focus much more on teaching and on the impact I may have on students. I still spend a lot of time on research, but it is more enjoyable now because I can pursue questions that interest me without the same pressure surrounding publication and tenure.
3. While visiting the Department of Finance at Aalto University in August this year, you taught an inspiring and slightly different PhD course titled “Finance and Growth: The Roles of Financial Development, Institutions, and Shareholder Primacy”. You manage to make the connections and links between finance, law, and economic growth clear and logical. The course has been an eye-opening experience for our doctoral students. How did you come up with an idea to structure the course around these important (complementary) topics?
I was first asked to teach a PhD course in 2011, when I was a professor at the University of Alberta. I decided to cover finance and growth for a couple of reasons. First, it had not really been covered in my own PhD program, so there was a great deal I wanted to learn myself. Second, it struck me as something that should be taught near the beginning of finance — not only to PhD students, but to all finance students. If finance does not matter for economic growth, if it is essentially just a sideshow, then why study it? Why should society devote resources to understanding financial markets and institutions if they do not have some broader economic or social impact? It turns out there is a lot of evidence that finance enables growth and thus contributes to the massive increase in living standards that we have enjoyed over the last couple of centuries. It seems like that should be taught to all finance students from the outset.
The law and finance and shareholder capitalism segments tend to follow naturally, at least in my mind. So, very generally, finance enables economic growth by providing capital to firms and entrepreneurs with promising projects but lacking resources. In some countries we see a lot of this; in others it is mostly absent. Why does finance vary like this around the world? One reason seems to be that laws that protect investors and creditors make them more willing to provide that capital. That is the law and finance part of the course.
Shareholder primacy is the idea that it is okay for the creation of shareholder wealth to be the firm’s goal. That sounds like a narrow goal that benefits few at the expense of many, but actually, it sends capital to the projects that create growth. Investor protection laws protect shareholders and help make sure they get to keep the gains from successful investments. If investors do not get to keep the returns from successful investments, then they will not invest, and all those promising projects that drive growth will never materialize. So, at least in my mind, that is how the three topics tie together.
4. You have written a great book “The Case for Shareholder Capitalism: How the Pursuit of Profit Benefits All”. Can you briefly explain the economic reasoning behind the claim that “the pursuit of profits benefits all”?
I think there are three interrelated reasons for this. The first is that profit is just a leftover or residual. A firm receives revenue from its customers, and from that it has to pay its employees, suppliers, lenders, and taxes. Profit is just the leftover from that and often the profit is negative. Thus, in a reasonably competitive market, a firm cannot earn profits without first creating value for other people. Customers have to be willing to buy its products, employees have to be willing to work for it, suppliers and lenders have to be willing to do business with it, and governments collect taxes. If a business owner enjoys any profits, it is only after all of these other parties have been compensated.
A second way to think about profits is as a signal that directs scarce resources toward what society values most. The essential problem in any economy is how to allocate scarce resources that have alternative uses. When a firm earns profits, it is because the value of what it created for society is greater than the value of the resources that it used. In the short run, a business may endure losses as it develops new products or builds its brand. But over the long run, persistent losses suggest that the resources being used could create more value somewhere else.
Finally, the pursuit of profit drives economic growth and all the benefits it has brought to humanity over the last couple of centuries. Three Nobel Prizes illustrate this. Robert Solow showed that long-run, persistent economic growth is driven by technological innovation. But creating an innovation can be costly, so why do people do it? Paul Romer showed that the profit motive is behind this. Firms will invest in risky R&D projects because a successful innovation can create wealth for the investors. Without the prospect of those returns, much of the incentive to innovate disappears. The most recent Nobel Prize (Joel Mokyr, Philippe Aghion, and Peter Howit) shows that growth is driven by creative destruction, where innovating firms replace existing firms. But here again, profit is what gives the incentive to innovate.
The consequences of sustained growth have been extraordinary. Around 1820, roughly three-quarters of the world’s population lived in extreme poverty, global life expectancy was under 30 years, and only about 10 percent of adults could read. Today, roughly one in ten people lives in extreme poverty, global life expectancy is about 73 years, and adult literacy is about 87 percent. So the broader is that the profit motive helps direct resources toward things people value, creates incentives for innovation, and thereby contributes to the economic growth that has dramatically improved human welfare.
5. When thinking about economic growth today and in the future, it’s impossible to ignore the impact of AI. How do you see AI’s role in this context?
Historically, innovation has been the fundamental driver of economic growth, so from that perspective I think AI should be a positive force. But we also know, going back to Joseph Schumpeter and more recently to the work recognized by the 2025 Nobel Prize in economics, that innovation produces growth through a process of creative destruction.
Creative destruction means that new technologies give us new goods and services, or better and cheaper ways of producing existing ones, but in doing so they also displace parts of the existing economy. We get something new and valuable, but something that existed before may disappear. That disruption can be very real for the people whose jobs, skills, or businesses are tied to the old technology.
I expect AI to work in much the same way. I think it will produce enormous benefits—perhaps new medical treatments and cures, major scientific discoveries, and large improvements in productivity. But it will also change many jobs, eliminate some jobs, and create entirely new ones. Not everyone will benefit at the same time, and not everyone will be happy about those changes.
We cannot know exactly what AI will create, but history suggests that technological change can profoundly disrupt the economy while ultimately expanding the range of things people can produce and do.
6. Please tell us about your research interests and how they have evolved over the years. What are you working on now?
I probably work on too many different things. But one long-running strand of my research has focused on capital market imperfections — the idea that stock prices can diverge from fundamental values — and that this has implications both for investors in stocks and bonds and for corporate investment in things like factories and R&D.
I have two current projects in that spirit that look at stock market bubbles. In one paper, we study China’s stock market, where retail investors play an especially important role and social media is a major source of information. We find that positive firm-level social media sentiment pushes prices up for about ten months, creating a bubble that eventually fully reverses. Interestingly, the underlying fundamentals actually improve and never deteriorate, so what we see is an overreaction to a genuinely positive signal. We also study how different investors respond. Short sellers and corporate insiders appear to recognize the overvaluation and trade against it, but they are too constrained and too small a force to correct prices. Institutions, by contrast, tend to trade with the sentiment. So the bubble persists in part because the investors who recognize the mispricing have limited ability to arbitrage it away.
More recently, I have started a project examining U.S. stock market bubbles. These include the technology bubble of the late 1990s and about 20 other episodes. The project is still at an early stage, but the questions are closely related: How do different types of investors behave as a bubble develops? Who rides it, who trades against it, and how do sell-side analysts evaluate stocks caught up in it? More broadly, I am interested in understanding why bubbles continue to occur and how different investors and analysts respond to them or perhaps help create them.
7. You are a Visiting Distinguished Professor at the Department of Finance at Aalto, and this is your second year with us. How has it been? Did your expectations about Aalto, Helsinki, and Finland align with what you’ve experienced so far?
It has been a great experience. My family and I have enjoyed our time in Helsinki. There is not really one particular thing I can point to — it is just a very comfortable and easy place for us to be. The city is convenient and manageable, and my wife and kids genuinely enjoy spending time there while I am at Aalto.
I had visited Helsinki a couple of times before coming to Aalto, but only in the winter. Obviously, summer in Finland is quite different and is a nice escape from the very hot and humid summers that we have back home in Virginia.
My experience at Aalto has been equally positive. The students are very strong and engaged, and the faculty have been welcoming. I have especially enjoyed having enough time in the department to get to know people rather than simply coming through for a seminar or a short visit.
8. Bonus question: Have you figured out why Finland is ranked as the world’s happiest country for the ninth consecutive year in the World Happiness Report?
My kids point to the licorice. I lean more toward salmon soup and the high quality of hockey in the Liiga. The new Liiga format might get you another nine years.
About Professor David McLean
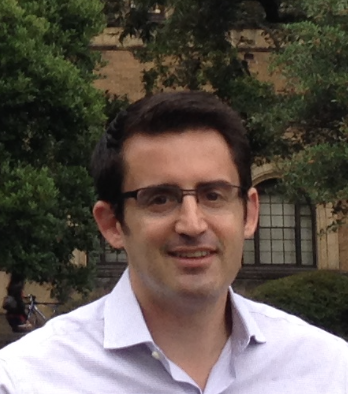
David McLean is Professor of Finance and the William G. Droms Chair at Georgetown University’s McDonough School of Business. His research focuses on capital market imperfections and their implications for asset prices and corporate investment. His research has won several awards, including the Amundi Smith Breeden Award for the best paper in the Journal of Finance, the Jensen Prize for the best paper in the Journal of Financial Economics, and the JFQA Sharpe Award. His research has been covered by The Economist, the Wall Street Journal, the Financial Times, the New York Times, and Bloomberg.
McLean is the author of The Case for Shareholder Capitalism: How the Pursuit of Profit Benefits All. He is an associate editor of the Journal of Financial and Quantitative Analysis and previously served as an associate editor of Management Science, the Journal of Empirical Finance, and other journals. He has taught at DePaul University, the University of Alberta, and MIT and held visiting appointments at Aalto University, ESCP Paris, and Hong Kong Polytechnic University. He was also a Shimomura Fellow at the Development Bank of Japan and a financial economist at the U.S. Securities and Exchange Commission. He holds a PhD in finance from Boston College and is a CFA charterholder.